
A trading equity curve simulator runs your strategy stats through thousands of randomized trade sequences — so you see possible account paths, drawdowns, and losing streaks before live capital is at risk. It is preparation, not prediction.
For planning tools, see our free trading calculators — including position sizing, drawdown recovery, and win rate calculators.
How this guide differs: This focuses on Monte Carlo equity curves from your performance metrics (psychology and risk planning). For replaying price history on charts, see how to backtest trading strategies and what is backtesting. For defining drawdown math, see what is maximum drawdown. Feed simulators from a trading journal with honest win rate and R:R.
What is a trading equity curve simulator?
Winning streaks feel invincible; losing streaks make you doubt the plan. An equity curve simulator replaces guesswork with a range of outcomes based on inputs like:
- Win rate
- Average risk-reward (R:R)
- Risk per trade (e.g. 1% of account)
- Number of trades to simulate
Example: 55% win rate, 2:1 R:R, 1% risk per trade — run 1,000 sequences of 100 trades each. You will not get one “guaranteed” line; you get a distribution of curves, worst-case drawdowns, and how often a 10-trade losing streak appears.
Benefits:
- Manage expectations — profitable systems still have deep drawdowns
- Build mental toughness — seeing a 10-loss streak survive in simulation reduces panic live
- Trade with discipline — stick to the plan when you know the statistical envelope
Simulation is not fortune-telling. It turns emotional reactions into probability-aware decisions.
Building a trading equity curve simulator: step-by-step
Whether you use a spreadsheet, Python, or a web tool, every equity curve simulator follows the same workflow. The goal is not one pretty chart — it is a distribution of account paths when trade order changes but your edge statistics stay the same.
Step 1 — Export honest stats from your journal. Pull win rate, average winner, average loser, and risk per trade from at least 100 closed trades. Use how to calculate win rate and your trading journal — not a cherry-picked month.
Step 2 — Set simulation length. Run 500–1,000 trades per path. Shorter runs exaggerate lucky streaks; longer runs show whether your edge survives boredom and drawdown.
Step 3 — Randomize sequence, keep statistics fixed. Each run shuffles wins and losses while holding win rate and R:R constant. That is Monte Carlo in plain English: same casino odds, different nights at the table.
Step 4 — Record tails, not averages. Note the 90th percentile max drawdown, longest losing streak, and how often the account dips below your psychological quit point. Pair this with our drawdown recovery calculator to see how much gain it takes to climb out of those valleys.
Step 5 — Stress one variable at a time. Re-run with 1% risk instead of 2%, or 60% win rate instead of 55%. A good trading equity curve simulator answers sizing questions before you change live behavior.
What an equity curve simulator shows that one backtest cannot
A chart backtest replays historical prices with fixed rules. An equity curve simulator replays your performance statistics in random order. Both are useful; they answer different questions.
| Question | Use this |
|---|---|
| Did my rules work on 2020–2024 data? | Backtesting |
| Can I survive a 12-loss streak at 1% risk? | Equity curve / Monte Carlo simulator |
| How much capital do I need for a 25% drawdown? | Simulator + maximum drawdown math |
If your simulated paths mostly rise but one in ten hits a 30% drawdown, that is not failure — it is information. Size and psychology should match the tail, not the median curve.
Core inputs (garbage in, garbage out)
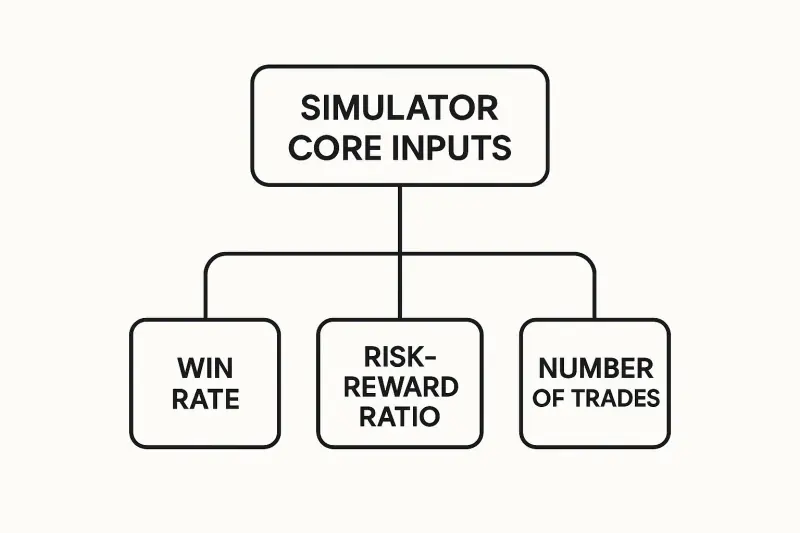
The engine runs on metrics from your journal — not hopes.
| Parameter | What it means | Why it matters |
|---|---|---|
| Win rate | % of winning trades | Drives frequency of streaks and recovery |
| Risk-reward ratio | Avg win size vs avg loss | Defines whether winners cover losers over time |
| Number of trades | Simulation length | Larger samples (500–1,000) smooth random noise |
Rules for honest inputs:
- Win rate — 60 wins in 100 trades = 60%; include every trade, including scratches
- R:R — 2:1 means average winner is 2× average loser (use journal averages, not best trade)
- Sample size — prefer 100+ real trades before trusting outputs; simulate 500–1,000 trade paths for stability
Collect metrics via how to backtest trading strategies or export from TradeReview/your journal.
How to read simulation results
Do not fixate on the highest ending balance. Study patterns that repeat across runs.
Metrics that matter
- Maximum drawdown — largest peak-to-trough drop; if simulations show 25% DD, plan capital and psychology for it (what is maximum drawdown)
- Consecutive losses — how many losses in a row are likely before you abandon a valid edge
Monte Carlo in plain terms
Each run shuffles trade order while keeping the same win rate and R:R. Run again — curves differ. That is the point.
You might see average max drawdown 15% with a 10% chance of 30% — plan for tails, not averages only.
Goal: stop chasing certainty; manage probabilities.
Putting the simulator to work
Test risk per trade
Many traders start at 2% risk per trade. Simulate 1% — curves often smooth with shallower drawdowns and similar long-term upside. One variable change, no months of live experimentation.
Stress-test edge improvements
Journal shows 55% win rate — simulate 60% with the same R:R. See impact on growth, drawdown, and streak length before changing live rules.
Questions to answer in simulation:
- Does the edge hold over 1,000 trades?
- What happens if R:R improves from 1.5:1 to 2:1?
- Can the system survive 10 consecutive losses at your chosen risk %?
Build discipline through simulation
The hardest opponent is usually you — not the market. Simulation is a mental gym: rehearse a five-trade live slump after seeing a 15-trade drawdown recover in Monte Carlo.
That exposure builds trust in positive expectancy — you think like a casino owner: short-term losses, long-term edge.
Pair simulation with consistent journaling (TradeReview, spreadsheet, or trading journal Excel template if you prefer sheets).
FAQ
How accurate is an equity curve simulator?
Only as good as your inputs. It mirrors historical performance statistics — not black swans or future discipline slips. Use 100+ real trades minimum for inputs.
How many trades should I simulate?
For the simulation run, use 500–1,000 trades. For the inputs, derive win rate and R:R from as much real data as you have.
Can it prove my strategy is profitable?
No proof — strong validation. If most paths rise with tolerable drawdowns, confidence goes up. If most paths blow up, refine before live size.
What is the best free equity curve simulator workflow?
Export win rate and R:R from your journal, run 500+ Monte Carlo paths in Sheets or code, and compare max drawdown at the 90th percentile — not the average ending balance. Feed inputs from the win rate and expectancy calculator if you are still building sample size.
Equity curve simulator vs backtesting?
| Equity curve / Monte Carlo | Chart backtesting | |
|---|---|---|
| Input | Win rate, R:R, risk % | Historical prices, rules |
| Output | Distribution of account curves | Trade list on past data |
| Best for | Risk psychology, position sizing | Rule validation on history |
Related reading
- Why every trader needs a trading journal — source data for simulations
- What is maximum drawdown — interpret simulator valleys
- How to backtest trading strategies — collect win rate and R:R
- Daily P&L tracking — session totals that feed simulator inputs
- Free trading calculators — drawdown recovery and win rate tools
- Risk management for traders — size positions to simulated tails